My Airtel

Screenshots
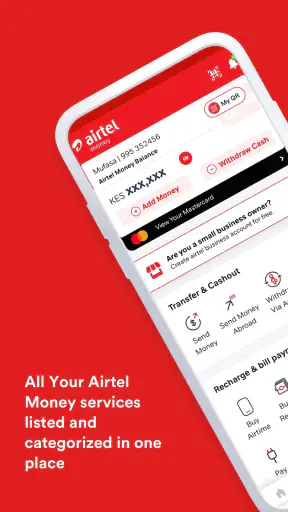
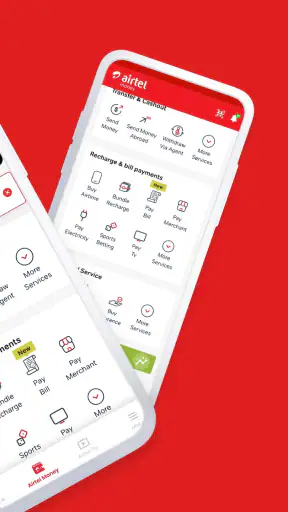
Details
- Rating
- 2.37K reviews
- Version
- 1.4.22
- Developer
- Airtel Africa
Analysis by Norviv
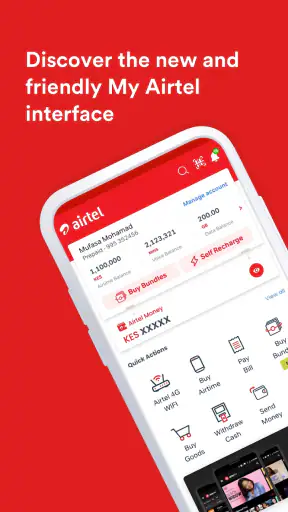
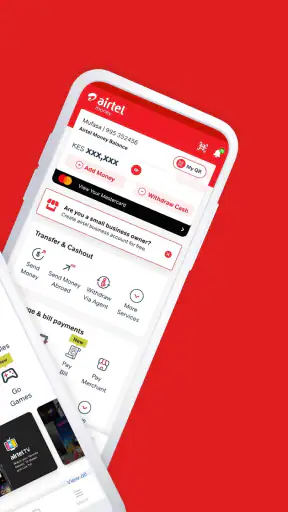
Managing mobile service usually becomes annoying at exactly the wrong moment: when data is nearly finished, a bill is due, or someone needs money moved quickly. My Airtel brings those tasks into one Lifestyle app from Airtel Africa, with its main value coming from the way it connects mobile recharge, bill payments, money transfers, and wallet activity in one place. I found that this matters less as a flashy feature and more as a practical change to my routine: instead of switching between separate services, I can begin with the Airtel account I already use and handle the next payment from there.
The app is free and suitable for Everyone, which makes it easy to try without committing to a subscription. It has built a large user base, with over 50 million installs and an average rating of 4.5 from around 581 thousand ratings. Those figures do not guarantee a perfect experience, but they do suggest that the app is solving a familiar problem for many people. My own impression is that its strongest audience is not someone searching for a broad financial-management tool, but an Airtel customer who wants everyday transactions to feel less fragmented.
One place for the transactions I repeat most
The central capability is the combination of mobile recharge and money movement. I can think of the app as a control point for routine Airtel-related tasks rather than as a replacement for every banking or payment app on my phone. That distinction is important. The benefit appears when my mobile account, a bill, and a transfer are part of the same week—or even the same errand.
For example, imagine leaving home with low data and remembering that a utility payment is also due. With separate services, I might open a banking app for the bill, a telecom menu for the recharge, and another wallet interface to send money. My Airtel is designed to reduce that hopping. I can open one app, choose the transaction I need, and continue from an account environment that is already connected to Airtel services. The real advantage is reduced friction between related tasks, not simply the number of buttons on the home screen.
This focus also explains why the app feels more useful for regular Airtel customers than for occasional visitors. If I rarely recharge an Airtel line or do not use the associated money features, there is less reason to keep another app installed. But for a household that frequently tops up several phones, pays recurring bills, or sends money through a wallet, having those activities grouped together can make the app part of a predictable weekly routine.
What the combined workflow feels like
In practice, I would start by opening the app and choosing the task instead of trying to remember which service handles it. A recharge is a direct need: select the relevant mobile account, enter the amount, and review the transaction before completing it. A bill payment follows a different path because the biller and reference details matter, while a transfer requires attention to the recipient and the destination. The useful part is not that these actions are identical; it is that they begin from the same application.
I recommend treating the app as a transaction tool, not as a place to rush through every screen. Before confirming a payment, I would check the phone number, account reference, recipient, and amount carefully. A unified interface can save time, but it can also make several different financial actions feel deceptively similar. The final review step deserves the same care I would give a bank or wallet app.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
One practical habit is to separate “checking” from “sending.” I can open the app to see what needs attention, then pause before authorizing a transfer or bill payment. This is especially useful when I am handling more than one family member’s mobile service. A quick glance at the selected number is worth the extra second, because convenience is only helpful when it does not encourage careless confirmation.
Another useful approach is to use it as a single starting point while keeping a personal record of important payments. I would not rely on memory simply because a transaction happened inside one app. For household budgeting, I would note the date, purpose, and recipient after a significant transfer or bill payment. This makes the consolidated workflow more useful without pretending that the app replaces a full budgeting system.
A realistic everyday use case
My favorite scenario for My Airtel is a busy morning before travel. I might need to add mobile credit, settle a household bill, and send money to a relative. The usual alternative is to move through several apps, authenticate repeatedly, and search for the correct service each time. With My Airtel, I have a better chance of completing the sequence from one familiar place. The time saving is not necessarily dramatic for one payment, but it becomes noticeable when these small tasks happen together.
This is also where the app can help someone who manages mobile service for other people. A parent may need to recharge a child’s line, while a small household may share responsibility for bills. The app’s value comes from reducing the number of separate starting points. I would still verify every destination individually, especially when switching between a personal recharge and a transfer to another person.
For a user who mainly wants to recharge a single line once in a while, the advantage is smaller. A carrier’s simpler USSD option, a bank app, or a standalone wallet may be faster for one familiar action. My Airtel becomes more compelling when the user wants a broader set of Airtel-connected transactions and prefers a visual interface over memorized codes or multiple service menus.
Where it differs from ordinary alternatives
Compared with a general banking app, My Airtel is more closely tied to mobile service and Airtel-related payments. A bank application may be better for viewing accounts, managing cards, reviewing detailed statements, or handling products outside the Airtel ecosystem. I would choose the bank app when my main goal is broader financial control. I would choose My Airtel when the task begins with mobile connectivity, an Airtel wallet, or a supported bill.
Compared with a standalone wallet, the appeal here is the direct relationship with Airtel services. A wallet may offer a wider range of payment destinations or a different interface, depending on the user’s country and preferred provider. My Airtel is more focused: it puts mobile recharge and related transactions close together. That focus can be a strength for an Airtel customer, but it is not automatically an advantage for someone who divides activity across several networks.
Compared with traditional carrier menus, the app offers a more visible way to review what I am about to do. Menus and short codes can be wonderfully quick when I know exactly what I need, but they are less comfortable when I am handling a bill or transfer and want to inspect the details. The app’s screen-based flow is easier to follow, although it depends on having the app available and a usable connection.
The tradeoffs I noticed
The biggest tradeoff is concentration. Putting recharge, bills, and transfers together is convenient, but it means the app becomes a more important doorway to several everyday tasks. If the app is unavailable, slow, or difficult to navigate at the moment I need it, several planned actions may be affected at once. For that reason, I would keep an alternative method in mind for urgent recharges rather than treating one interface as my only option.
There is also a learning curve created by the app’s breadth. Someone who installs it only to top up a phone may encounter options for payments and money transfers that are not immediately relevant. I prefer to identify the one or two actions I use most and ignore the rest until needed. That keeps the home experience manageable and reduces the chance of selecting the wrong transaction type.
Security awareness remains essential. The app deals with actions that can move money or add value to a mobile account, so I would avoid confirming anything while distracted or handing an unlocked phone to another person. I would also review the recipient and amount every time rather than assuming that a previous transaction has carried over correctly. These are not criticisms unique to My Airtel, but the app’s convenience makes disciplined checking more important, not less.
Country and account context can affect how useful the experience feels. Airtel operates across different markets, and the exact payment choices available to a user may depend on the local service environment. I would therefore judge the app by the tasks I actually need in my location, not by assuming that every Airtel customer will see the same practical value. The core idea remains clear, but the usefulness of each part depends on whether it matches my daily services.
Small habits that make the app more useful
I would begin with a simple personal map of my recurring tasks. If recharge is the only regular need, I would use the app for that and avoid exploring unrelated sections until necessary. If I also handle bills or transfers, I would group those tasks mentally by purpose and pause between them. This sounds basic, but it prevents the unified interface from turning several unrelated payments into one rushed session.
For repeated household use, I would prepare the information I need before opening the app: the correct phone number, bill reference, or recipient details. That makes the transaction quicker while preserving a deliberate final check. The non-obvious benefit is that the app works best as the execution step of a prepared routine, not as a place where I search for details while already under pressure.
I would also use transaction records as a prompt for personal reconciliation. After paying a bill or sending money, I would make sure the result matches my own notes or household plan. The app can centralize actions, but my budget still needs a separate view if I want to understand where money went over a month. This is a useful boundary: My Airtel can simplify payment execution without becoming my complete financial diary.
Who should install it—and who should skip it
I would recommend My Airtel to Airtel customers who regularly recharge, pay supported bills, transfer money, or use an Airtel wallet. It is particularly suitable for people who dislike switching among carrier menus, banking apps, and wallet services. Families and users who manage more than one mobile-related task stand to gain the most because the consolidated workflow removes repeated app changes.
It is also a reasonable choice for someone who prefers a visual app to short codes or separate service channels. The free price lowers the barrier to trying it, and the Everyone age rating makes it broadly approachable. The developer is Airtel Africa, so the app feels most naturally suited to people already within that service ecosystem rather than users looking for a carrier-neutral payment hub.
I would skip it if my mobile provider is not Airtel, if I already have a bank or wallet app that handles every required task more comfortably, or if I only need the fastest possible one-off recharge and prefer a simpler method. I would also avoid making it my sole emergency option until I had used it enough to understand my normal transaction flow. Convenience is valuable, but reliable backups matter when mobile access or payment timing is urgent.
Long-term value and current fit
My Airtel has been available since August 28, 2019, and the current version is 1.4.22. It supports devices running Android 8.0 or later, so compatibility is worth checking before installation. The large install base and strong average rating show that the app has broad appeal, but I would still focus on whether its combined workflow matches my own Airtel usage.
After using it as a practical transaction hub, my view is positive but specific. I would not install it because it promises to replace every financial tool on my phone. I would install it because keeping mobile recharge, bill payments, and money transfers close together can make recurring errands easier to organize. The best result comes from using that convenience carefully: prepare the details, review the destination, confirm the amount, and keep another route available for urgent situations.
My final recommendation is simple: if Airtel is central to the way you recharge and move money, My Airtel is worth trying as your everyday starting point. Its strength is the connection between tasks that normally feel separate. If your needs are broader than Airtel services or you already have a smoother all-purpose banking setup, it may add little. For the right user, though, My Airtel turns a scattered set of small chores into one more coherent routine.
Frequently Asked Questions
01What is My Airtel and what can I do with it?
My Airtel is Airtel’s official self-service app for managing eligible mobile, broadband, and other Airtel services, depending on your country. After signing in with your Airtel number, you can usually check balances and data usage, recharge or pay bills, activate selected packs, review transaction history, and access customer support. Available features may differ by region and account type.
02Is My Airtel free to download and use?
The My Airtel app is generally free to download from the official Google Play Store or Apple App Store. Airtel may also provide access without charging standard app data in some markets or for certain services, but this is not universal. Normal mobile data charges can apply, and payments, recharges, subscriptions, or purchased bundles are billed separately according to your plan.
03How do I sign in to My Airtel?
Sign-in normally requires an active Airtel mobile number or another account identifier supported in your market. The app may verify you with a one-time password sent by SMS, while some versions also support email, account credentials, or biometric access after setup. Make sure your SIM can receive messages and avoid sharing verification codes with anyone.
04Can I use My Airtel to recharge, pay bills, or manage multiple numbers?
In supported countries, My Airtel lets you recharge prepaid accounts, pay postpaid or broadband bills, purchase data and voice packages, and view payment details. Some versions also allow several Airtel numbers or services to be linked to one account, although permissions and available payment methods vary. Check the app carefully before confirming a transaction, because completed payments may be difficult to reverse.
05Is My Airtel safe, and what should I do if the app does not work?
My Airtel is safest when downloaded from Airtel’s verified store listing and kept updated. Use a secure connection, protect your phone and account credentials, and never disclose OTPs or payment information through unofficial messages. If the app crashes, shows incorrect details, or fails to load, update it, restart your connection, clear its cache, and contact Airtel support through official channels.


